

🌍 Macro
My view hasn’t changed in several weeks.
Liquidity, corporate credit, earnings growth and the AI theme all point to higher stock prices in the mid term. Credit conditions remain healthy.
The disruptor is inflation via Hormuz. The strait is still effectively closed, but Brent sits at $88 rather than $120. Supply destruction and demand destruction have cancelled each other out. That’s a balance, not a resolution.
In the background, the consumer is being squeezed. Wages growing 3.2% against 3.4% inflation means real wages have been negative for four straight months. It doesn’t show up in this quarter’s earnings. It will show up eventually.
I keep watching the 10-year. It remains elevated at 4.685% — and here’s what’s interesting: inflation has fallen 80bp since March while the 10-year has risen 63bp. That tells me the bond market isn’t pricing inflation. It’s pricing term premium: fiscal supply, a credibility question after three FOMC dissents for a hike, and a new Fed Chair who no longer telegraphs his intentions.
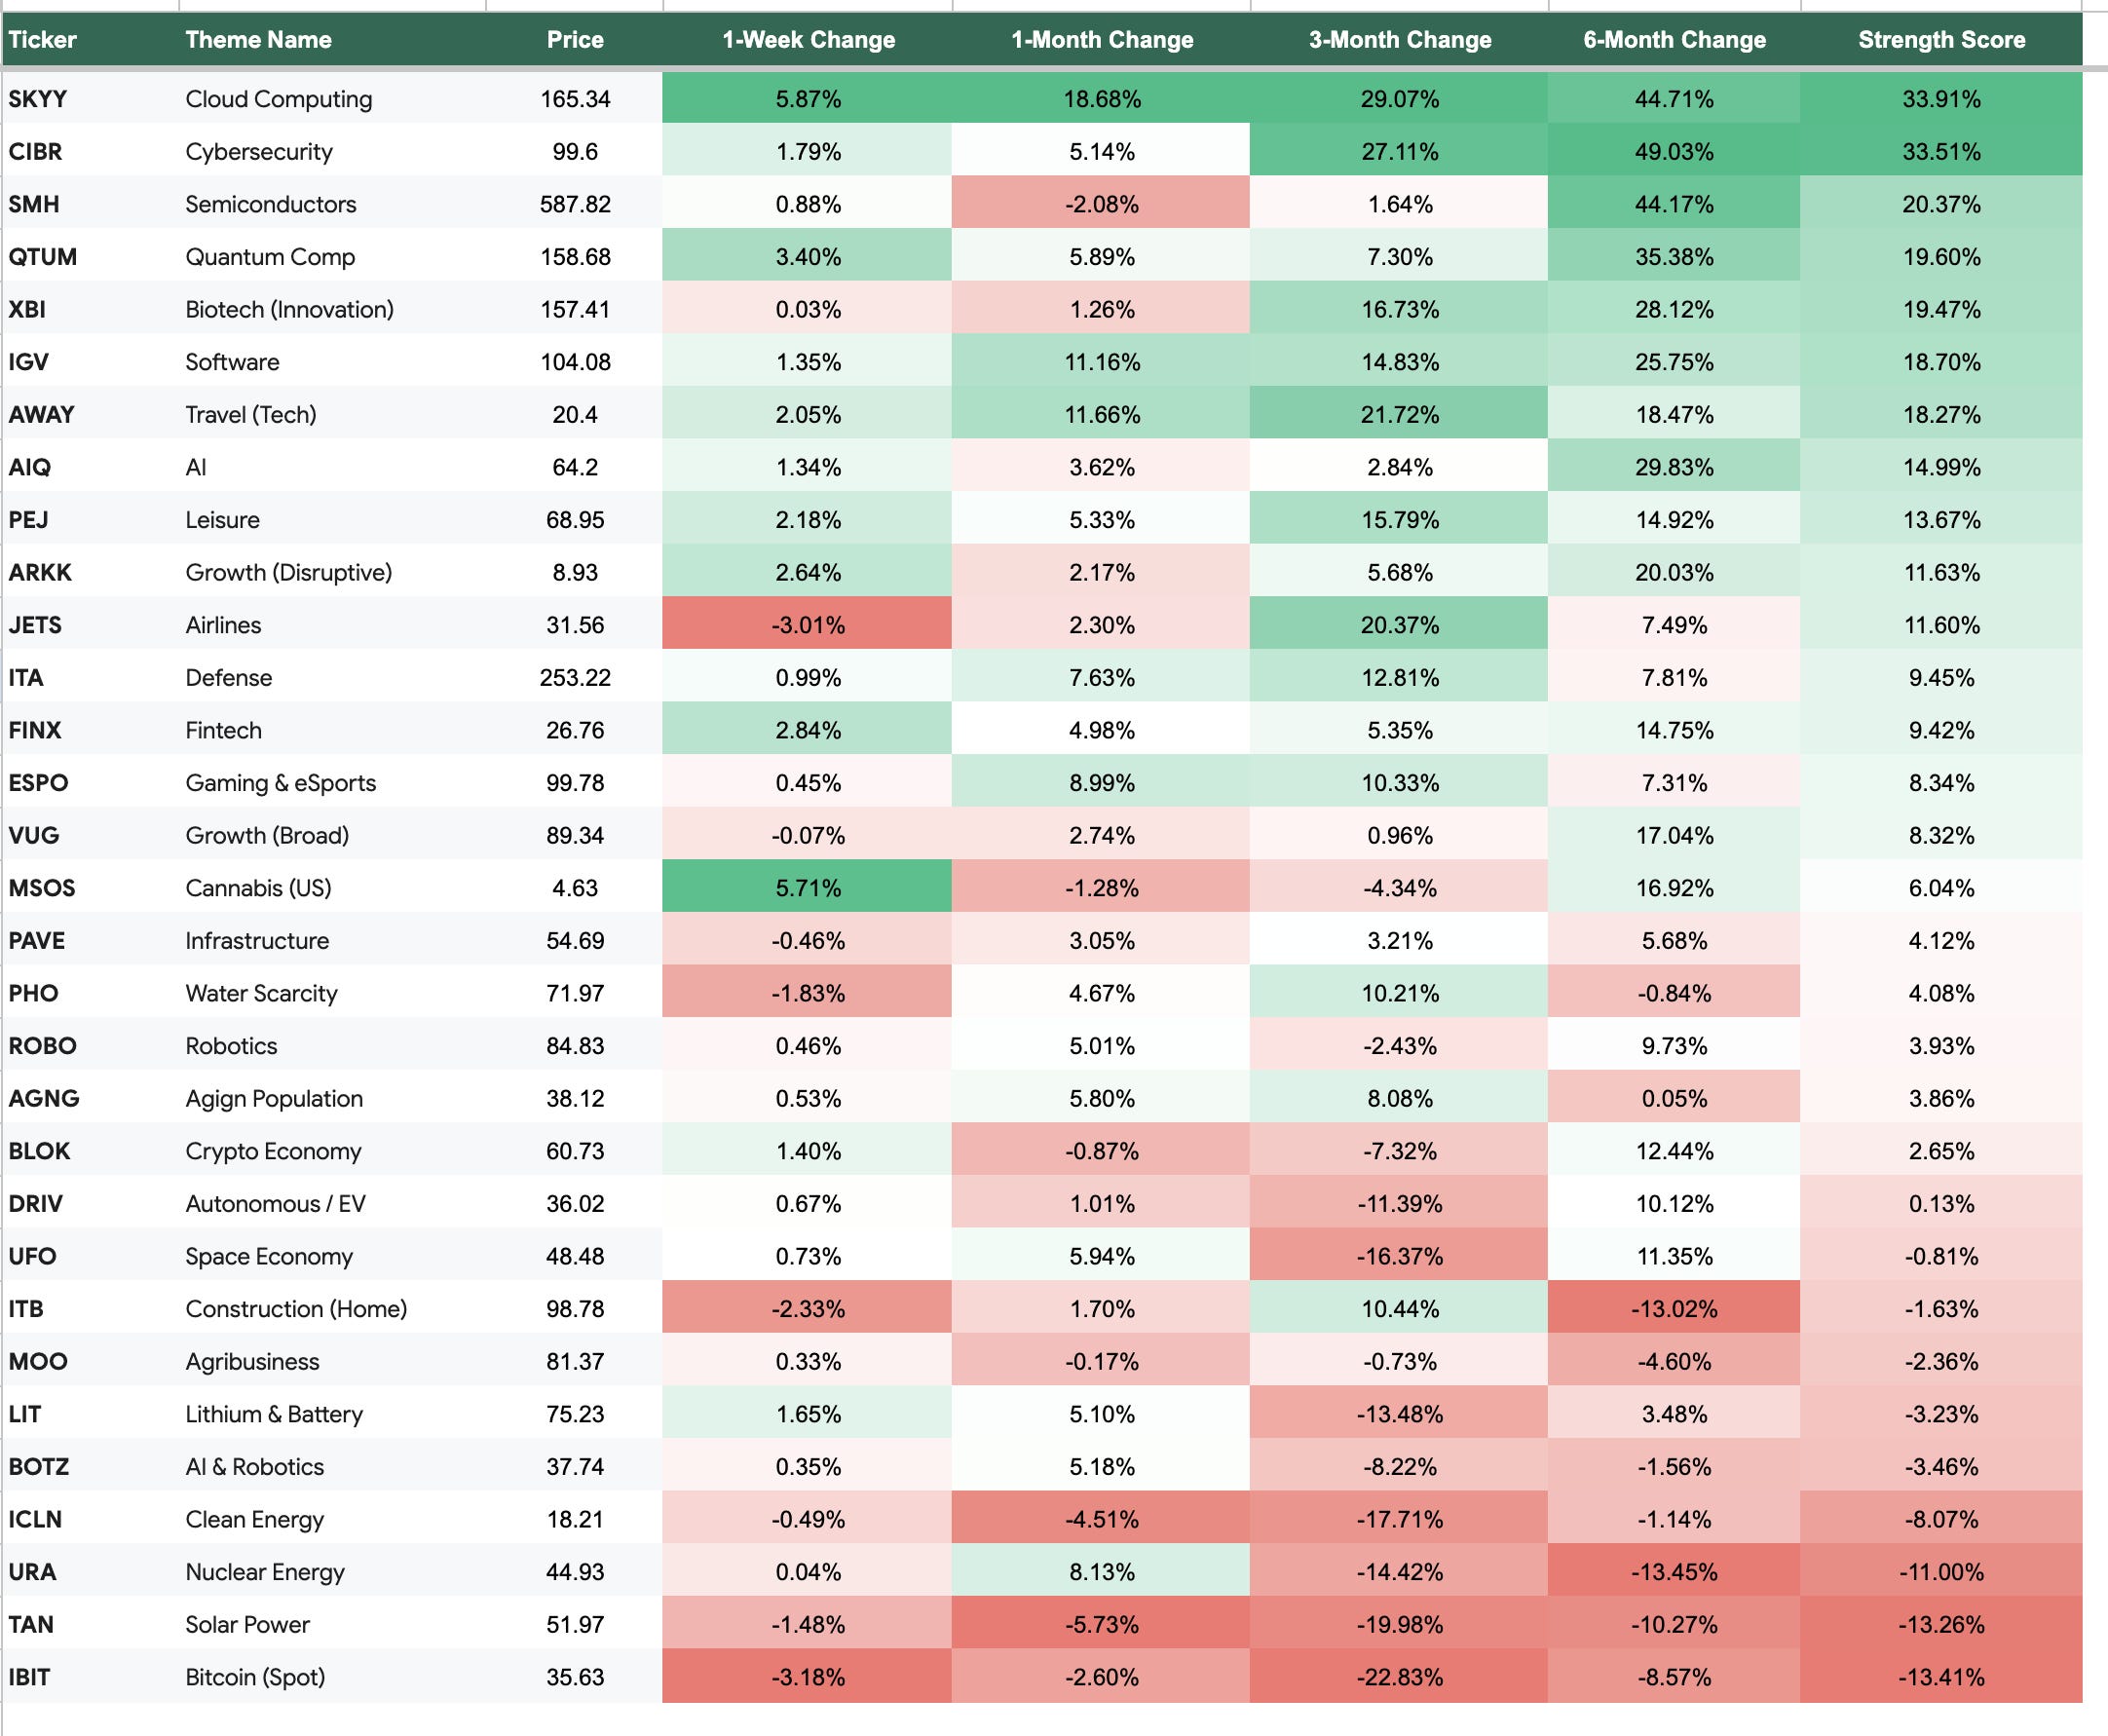
The practical consequence: even if inflation keeps falling, yields may not. Anything that needs cheap money (=low interest rates) stays under pressure. That’s why solar (example) is down ~20% over three months while oil is up 23%.
📊 Index and Sectors
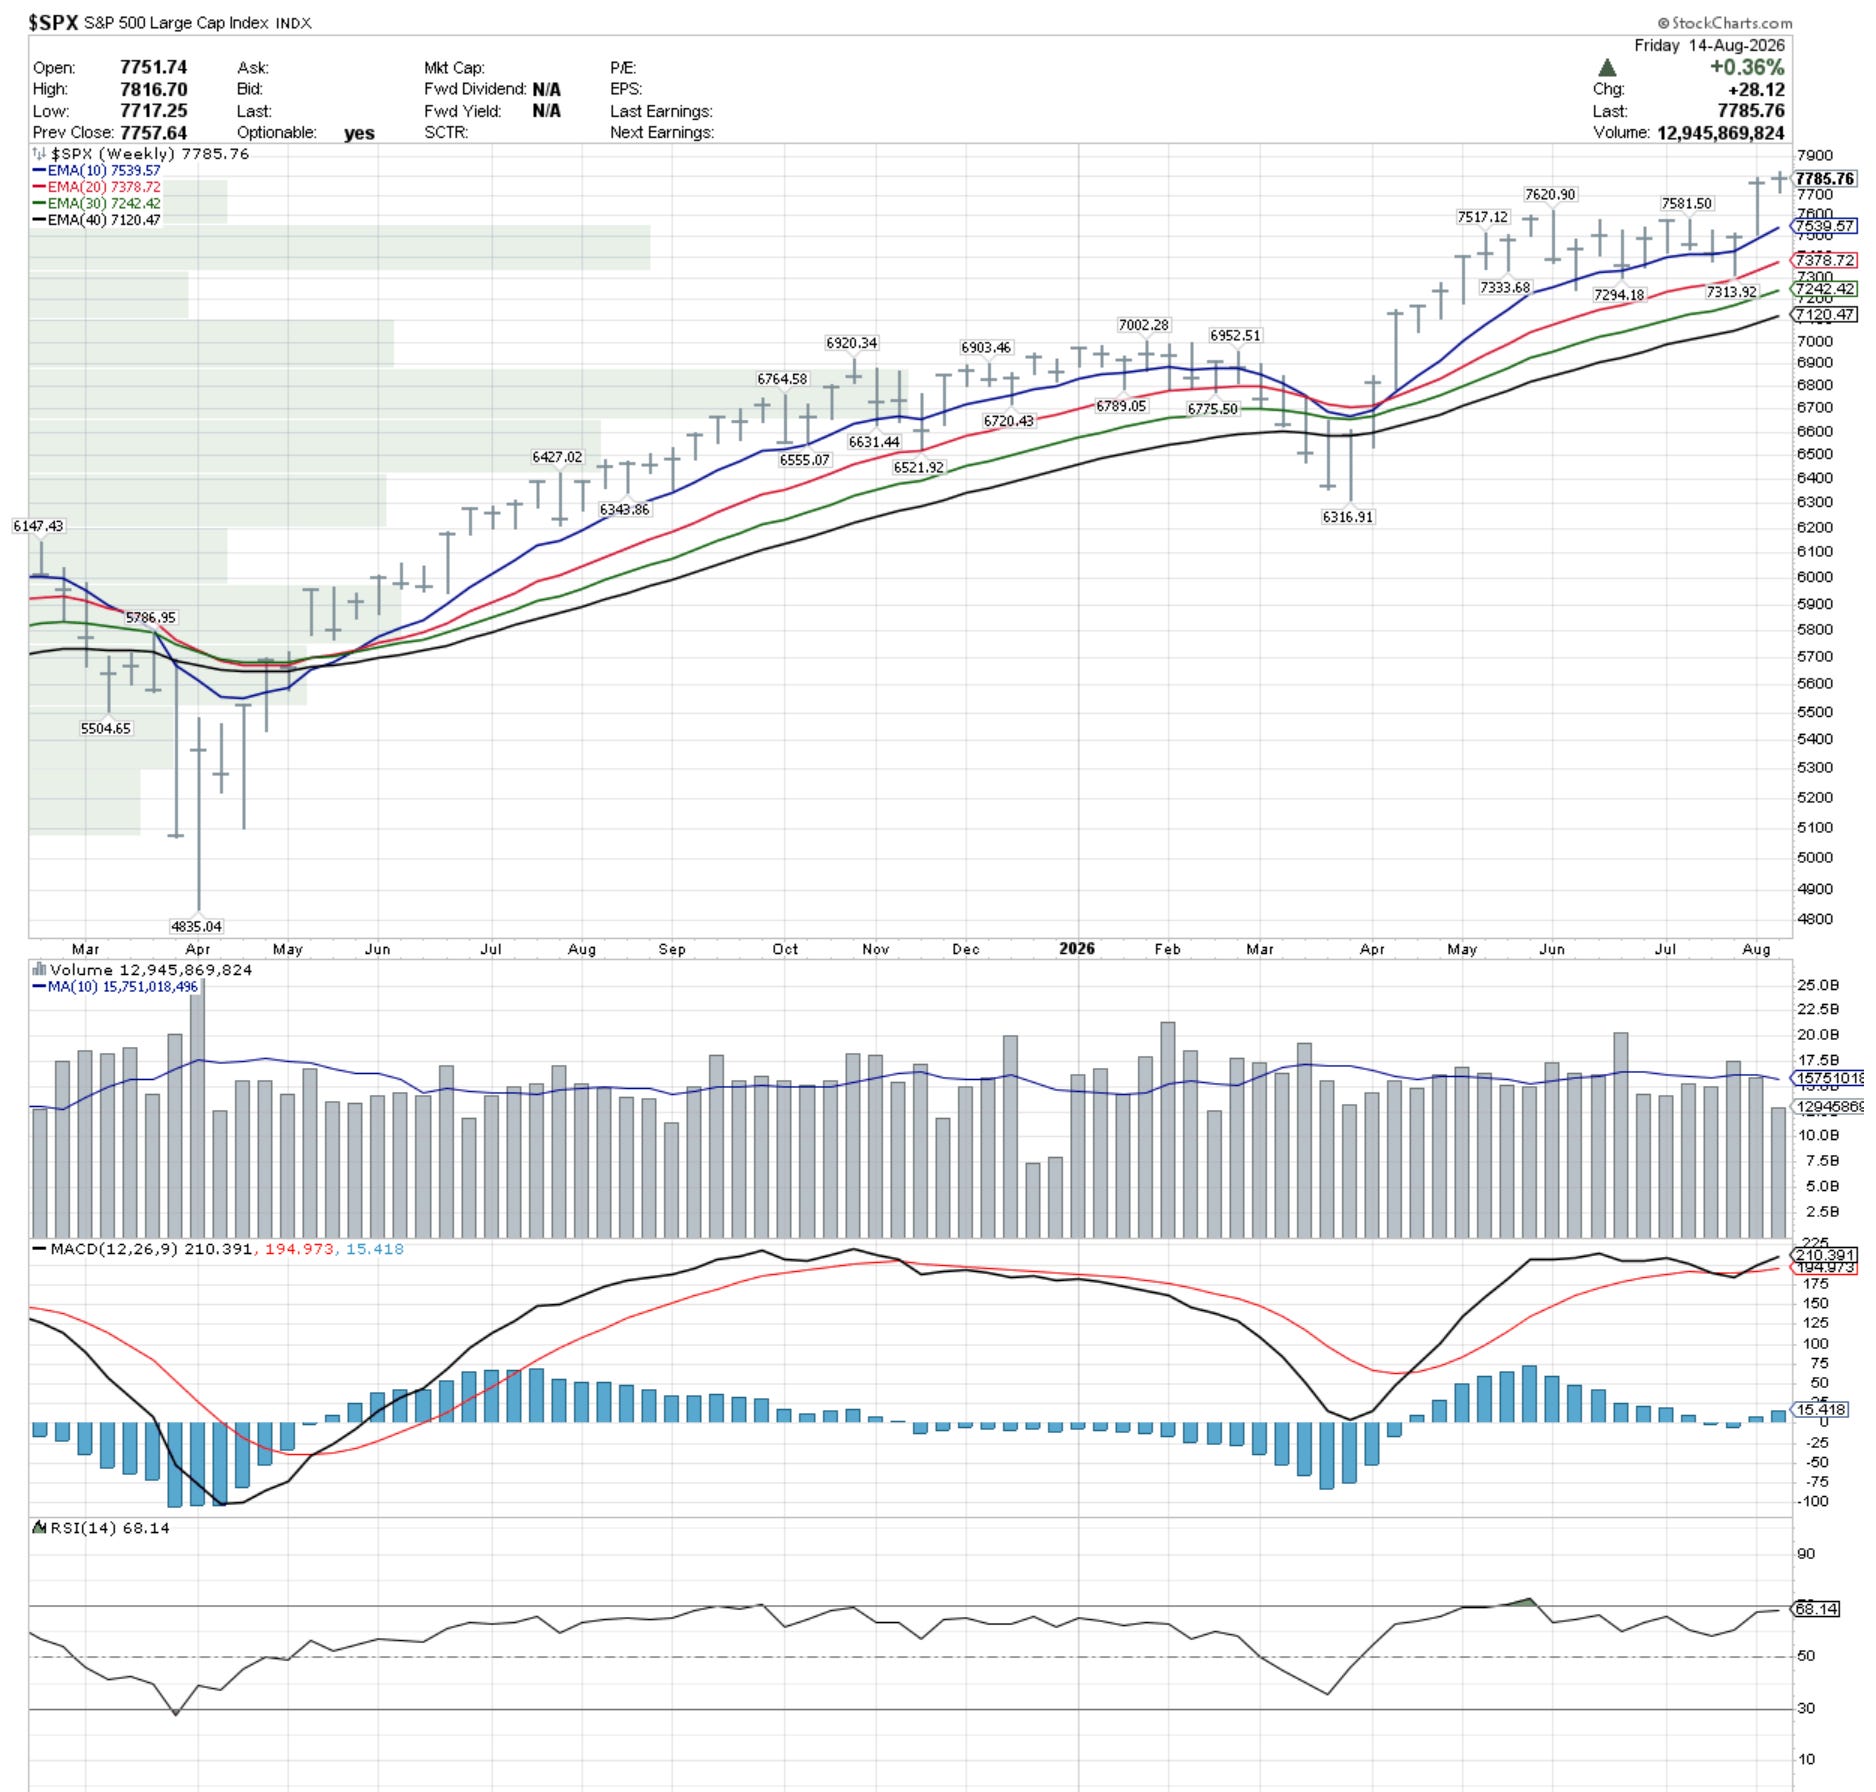
The S&P 500 remains in a confirmed uptrend — above all rising weekly moving averages, +23% off the March low.
Under the hood, technology is still the strongest sector. The market has decided that despite Hormuz, AI is an investment cycle that stays.
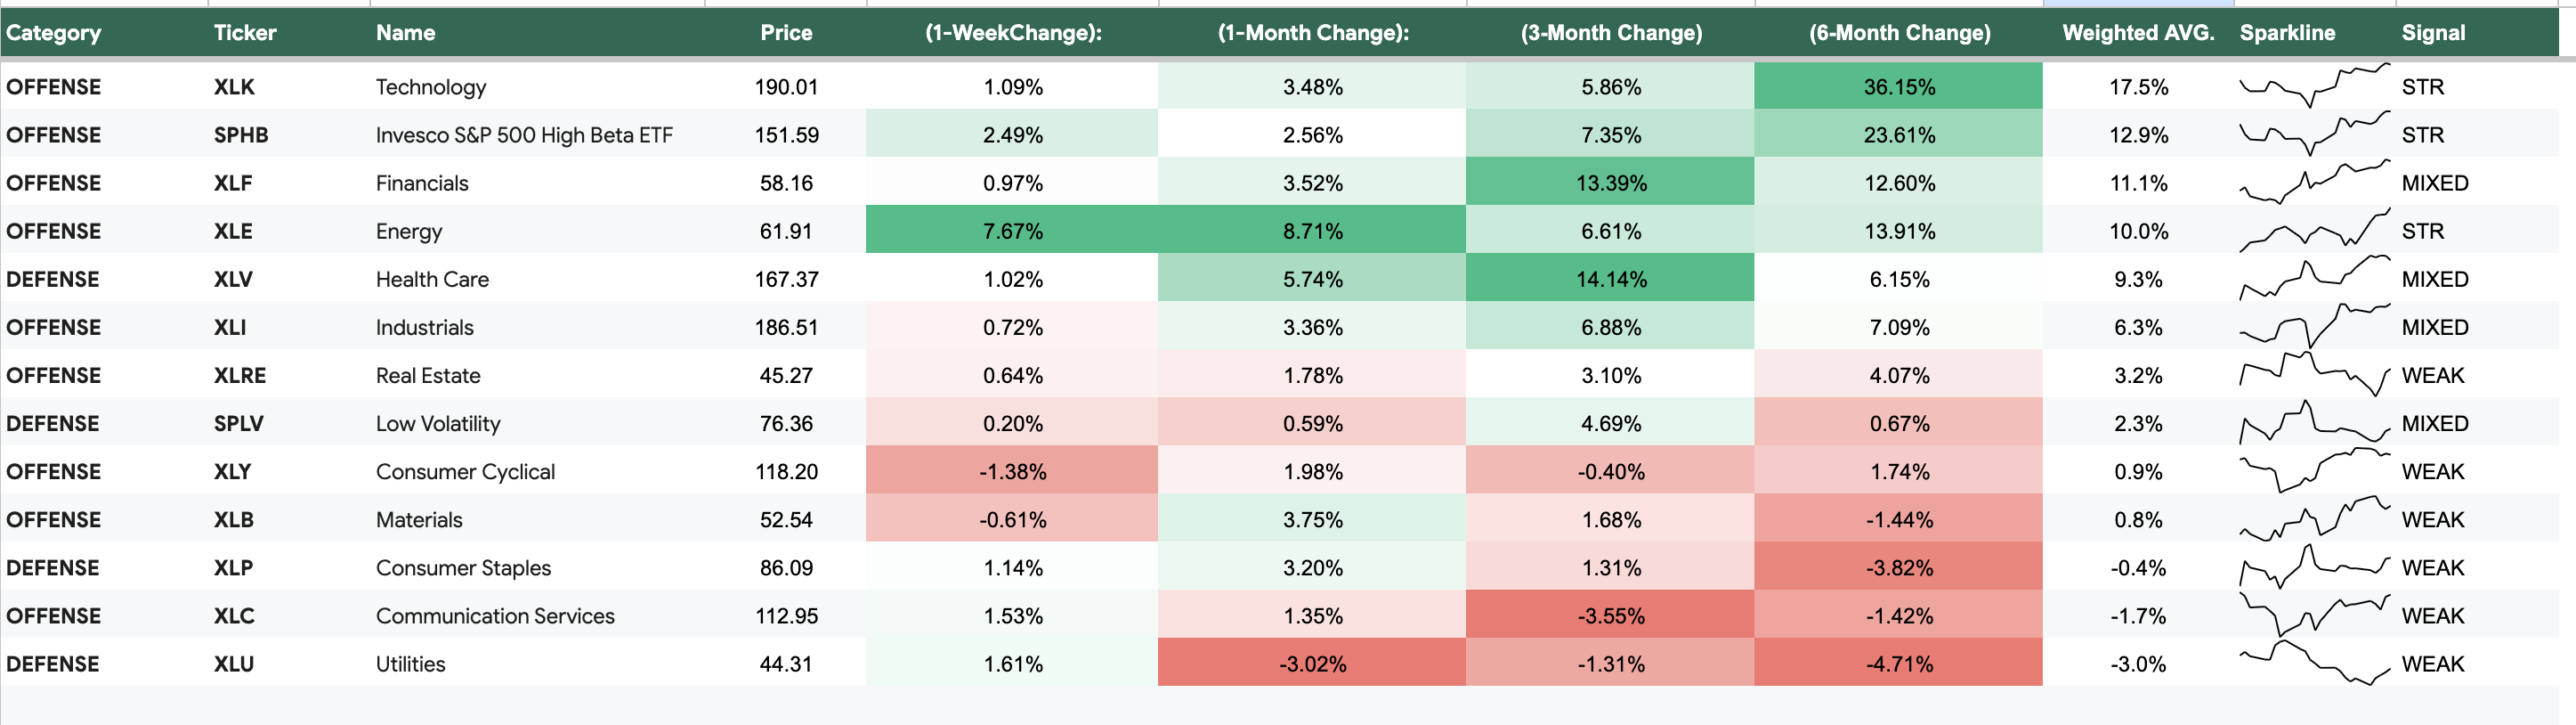
But there’s a split worth flagging. Tech leads on price while sitting mid-pack on participation. Financials are the mirror image: the highest breadth reading of any sector, with only middling performance so far. Health care and industrials show the same pattern.
Breadth usually leads price. That makes me more interested in financials, industrials and health care than in chasing what already ran.
Energy has been strong over the past month — and it’s a binary bet on Hormuz. Can I trust it?
One caveat on everything above: August is a low-volume month. The index itself is trading ~18% below its ten-week average. Moves exaggerate in both directions. I’m reading this tape with that discount applied.
📅 The calendar that matters
Three weeks that will settle a lot:
Aug 26 (PM) — NVDA earnings
Aug 28 (AM) — Warsh’s first Jackson Hole keynote as Chair
Sept 11 — August CPI
Sept 16 — FOMC, hike-or-hold still close to a coin flip
The two biggest events land 36 hours apart, in the thinnest liquidity of the year. Volume returns the week of September 8 — the same week CPI and the FOMC hit. That’s when a breakout will mean something.
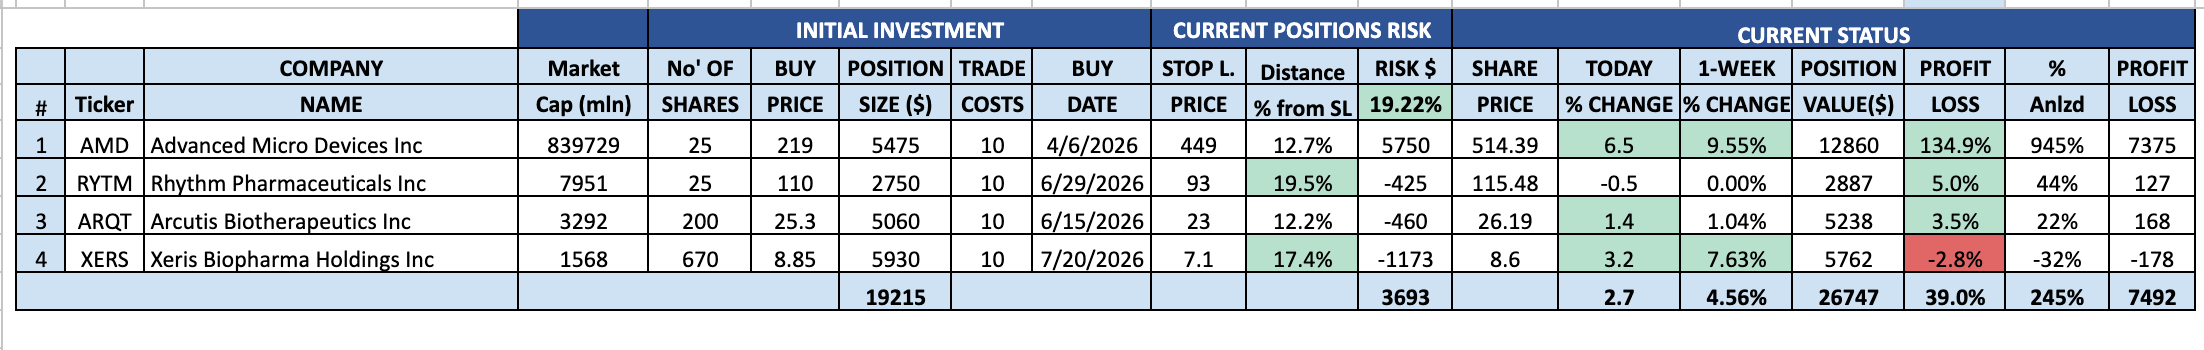
🚀 10X Momentum Portfolio
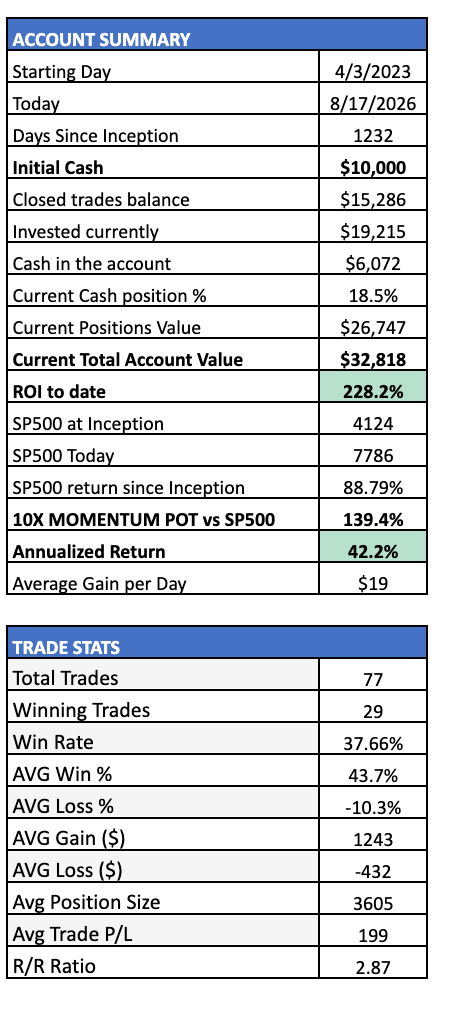
No additions this week. I scored three candidates and none cleared the gates. Updated stop levels below.
💎 10X Easy Doubles Portfolio
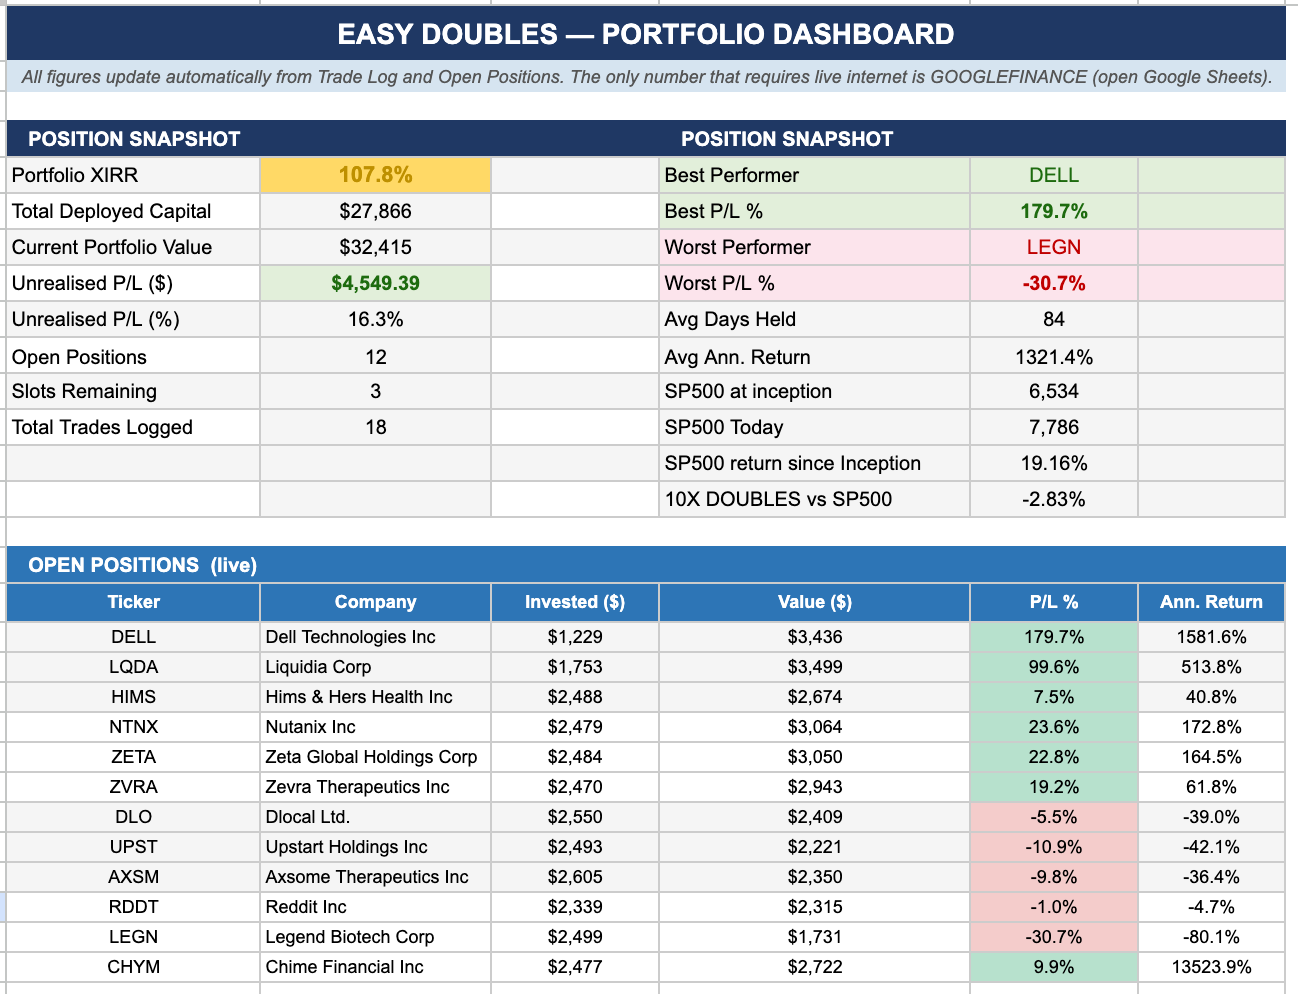
As shared last week, I sold ARDX and bought CHYM. Current portfolio below.
I’m also watching LQDA and LEGN for a possible sell. Let’s see what they do this week.
🎯 10X Best of ARKK Portfolio
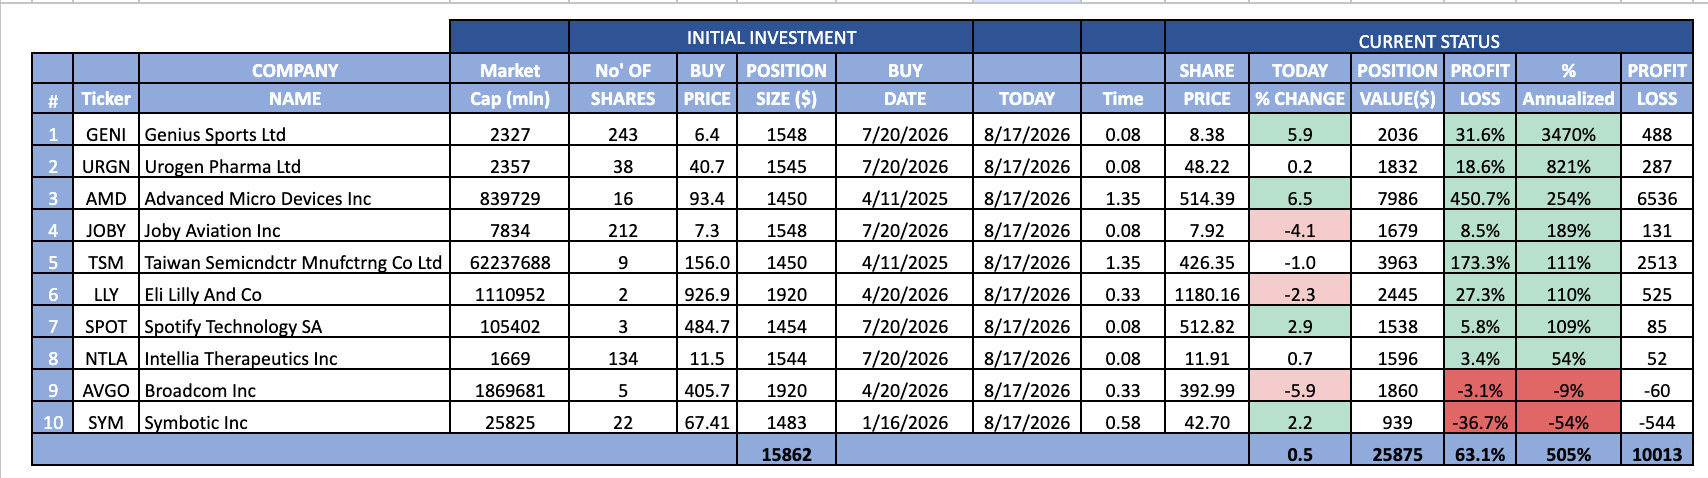
Quick update on the recent rebalancing.
All additions from July 20th are green — GENI +32%, URGN +19%, JOBY +8%, SPOT +6%, NTLA +3%. One month in.
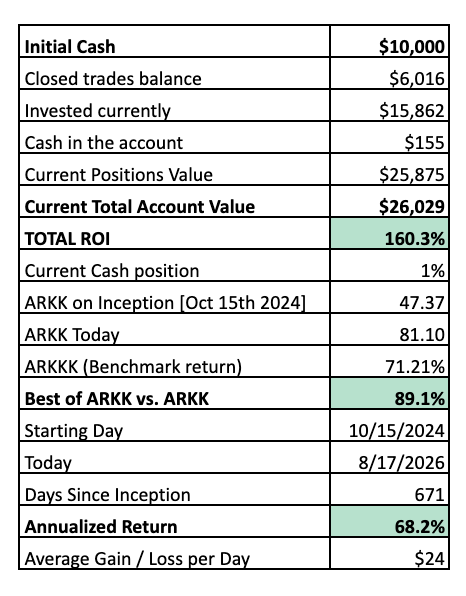
ROI since inception: +160% (68% annualized).
👀 Watchlist
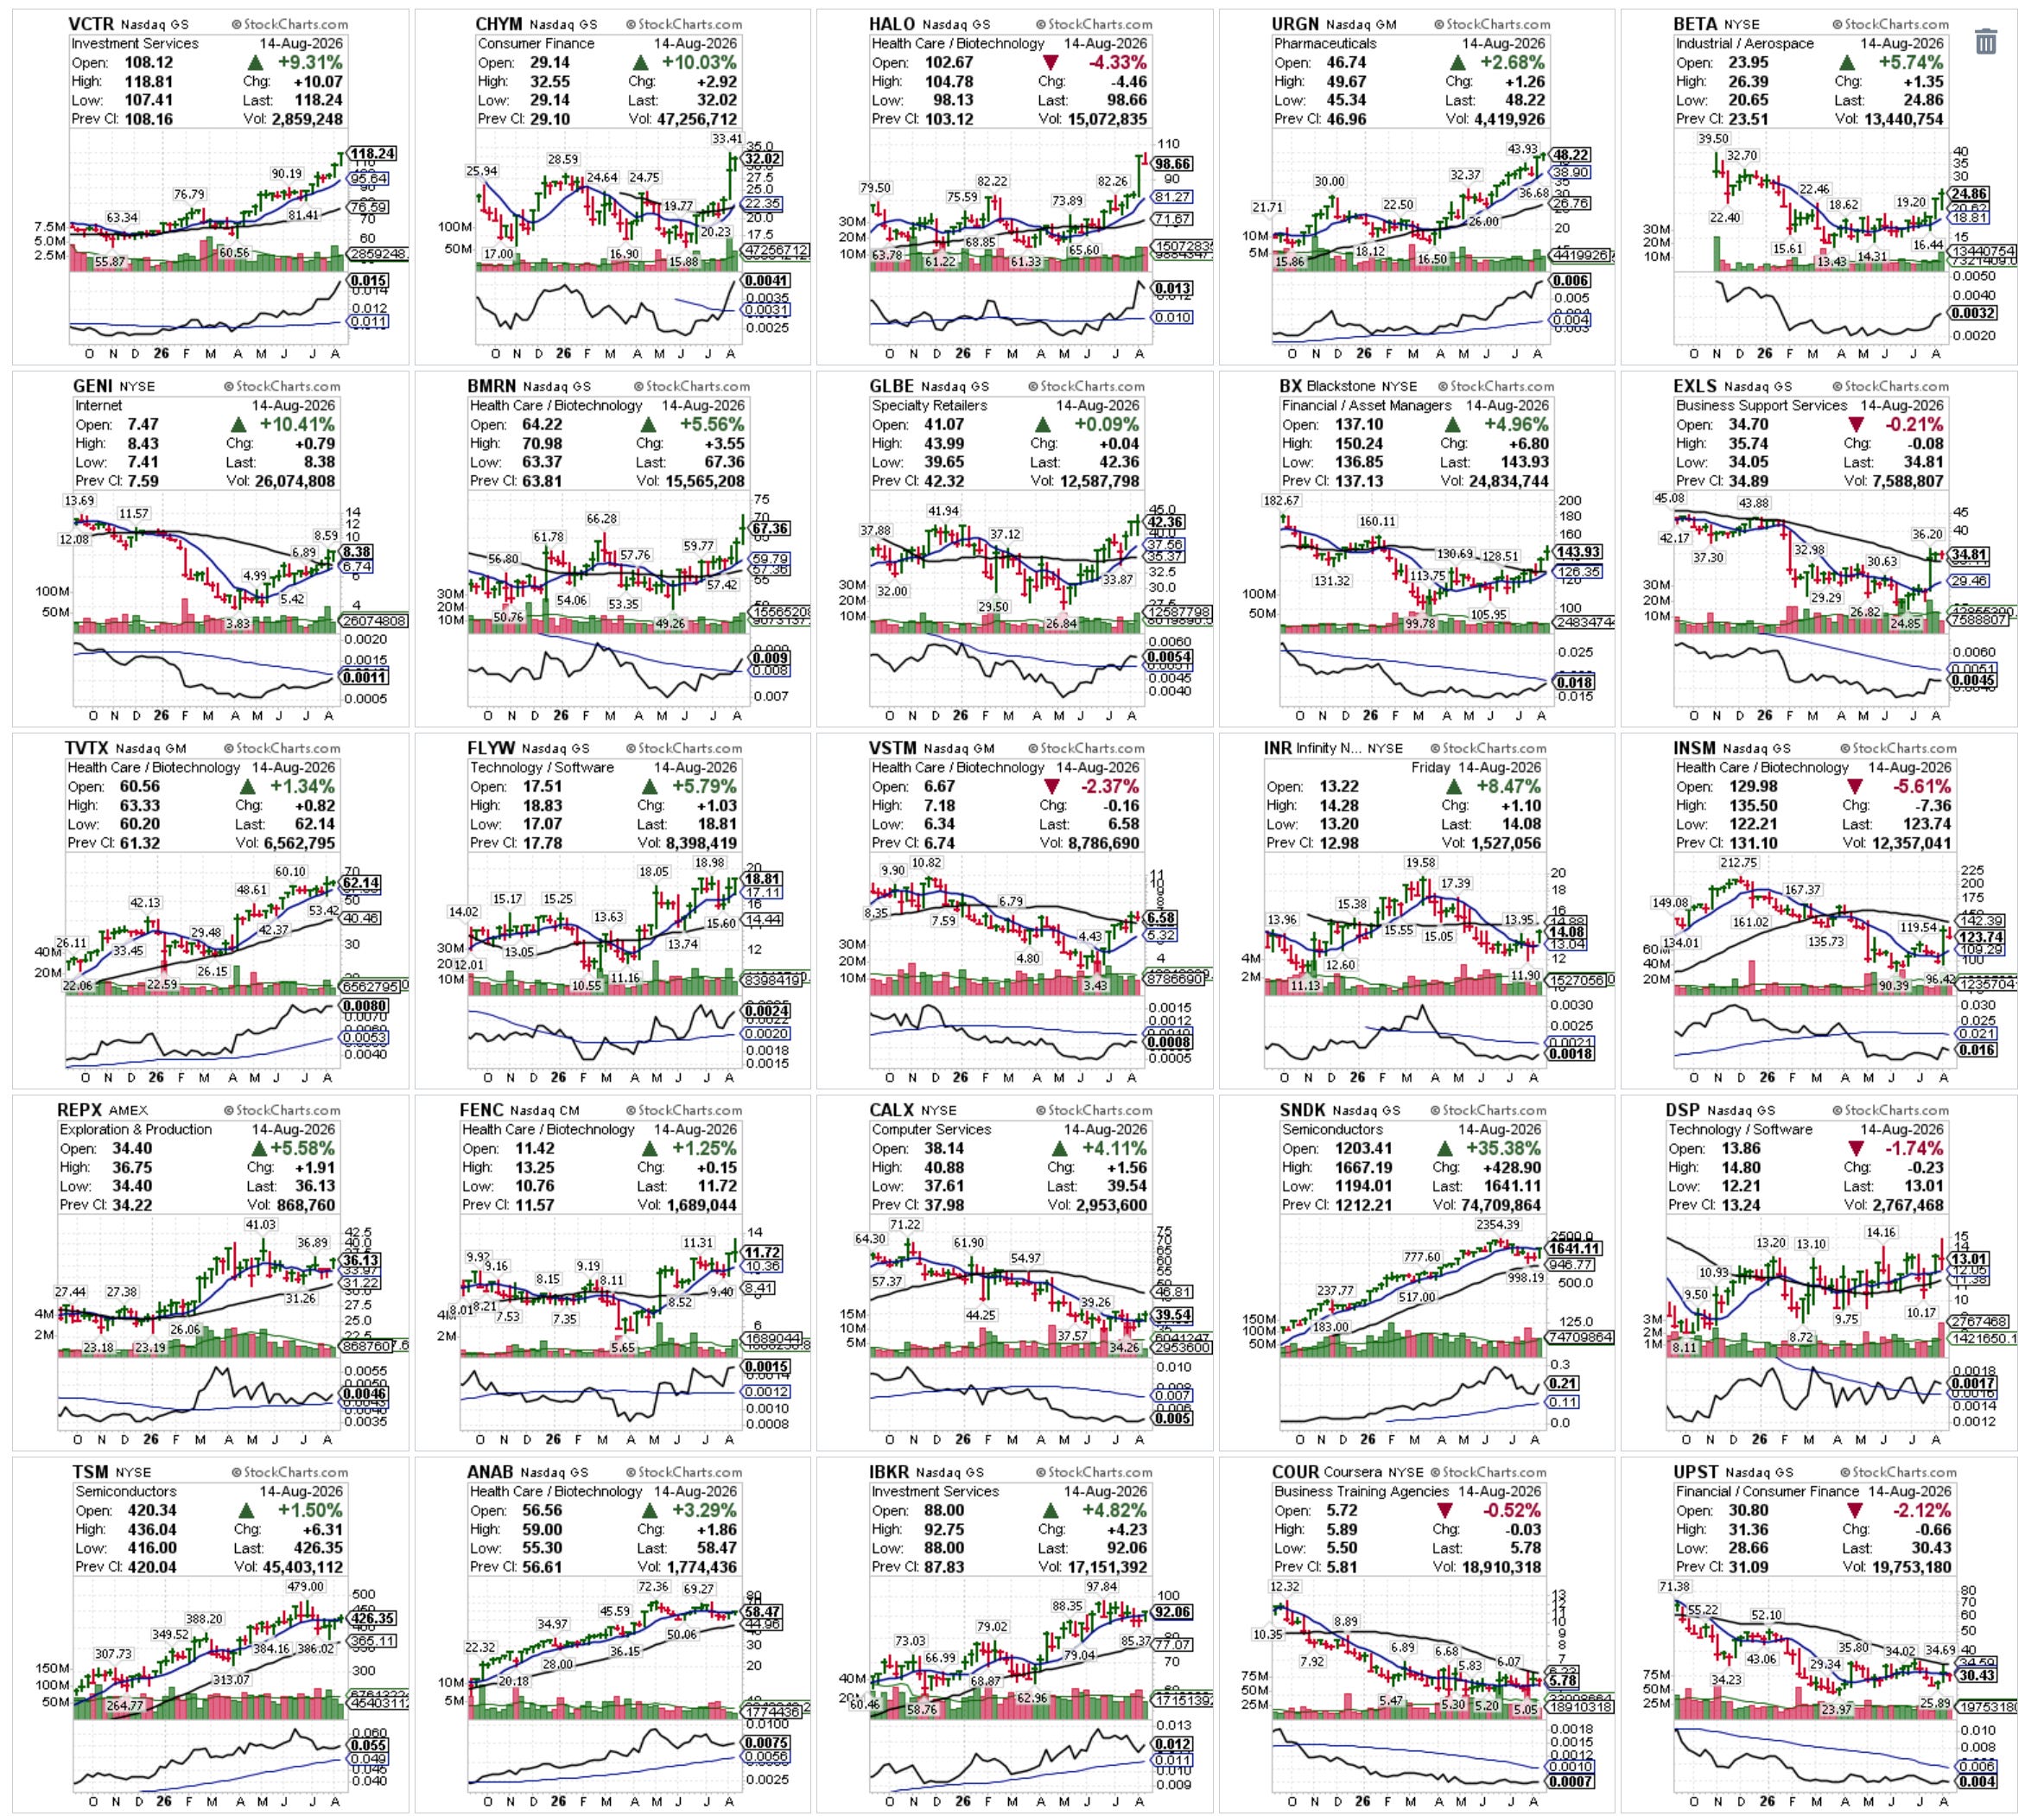
From one of my watchlists, best-performing names, ordered by 2-month relative strength, highest to lowest.
This is not investment advice. Please consult a licensed financial advisor before making any investment decisions.
Disclosure: This content has been reviewed using artificial intelligence to enhance readability and ensure grammatical accuracy.